Retiring at 41 on $360,000 in Quebec
Short answer: With about $360,000 saved at 27 and $25,000 a year going in, a Quebec saver who stops work at 41 can spend about $3,500 a month ($42,000 a year) after tax. His current spending is our estimate, about $4,700 a month, so retiring at 41 would mean spending less.
Based on a real question on Reddit, filled in with our assumptions and run in the WisePlan Wealth app. All amounts are after tax, in today's dollars.
A 27-year-old in r/fican asked whether he could retire at 41. He lives in Quebec, earns $110,000 to $120,000 and invests about $25,000 a year. We'll call him Olivier. We looked for the most he could spend if he stopped at 41.
The setup
- From the question and his other posts: age 27, Quebec, earns $110,000 to $120,000, owns a condo
- From his posts: about $260,000 in RRSP and TFSA (both maxed) and about $100,000 non-registered; invests about $25,000 a year
- Our assumptions: $170,000 RRSP, $90,000 TFSA, $100,000 non-registered ($85,000 cost basis); saves $12,000 RRSP, $7,000 TFSA and $6,000 non-registered a year until mid-2040 (41)
- Our assumptions: his workplace pension is left out (he said he ignores it), and the condo and mortgage are outside the plan
- Our assumptions: QPP about $700/month at 65 (low because he stops at 41) and OAS $762.50/month at 65
- Spending is an estimate: he didn't say what he spends. From his pay, tax and savings we estimate about $56,000 a year ($4,700/month) today
- Plan runs to 95, with default return and inflation assumptions
See the answer, year by year
Loading the interactive plan…
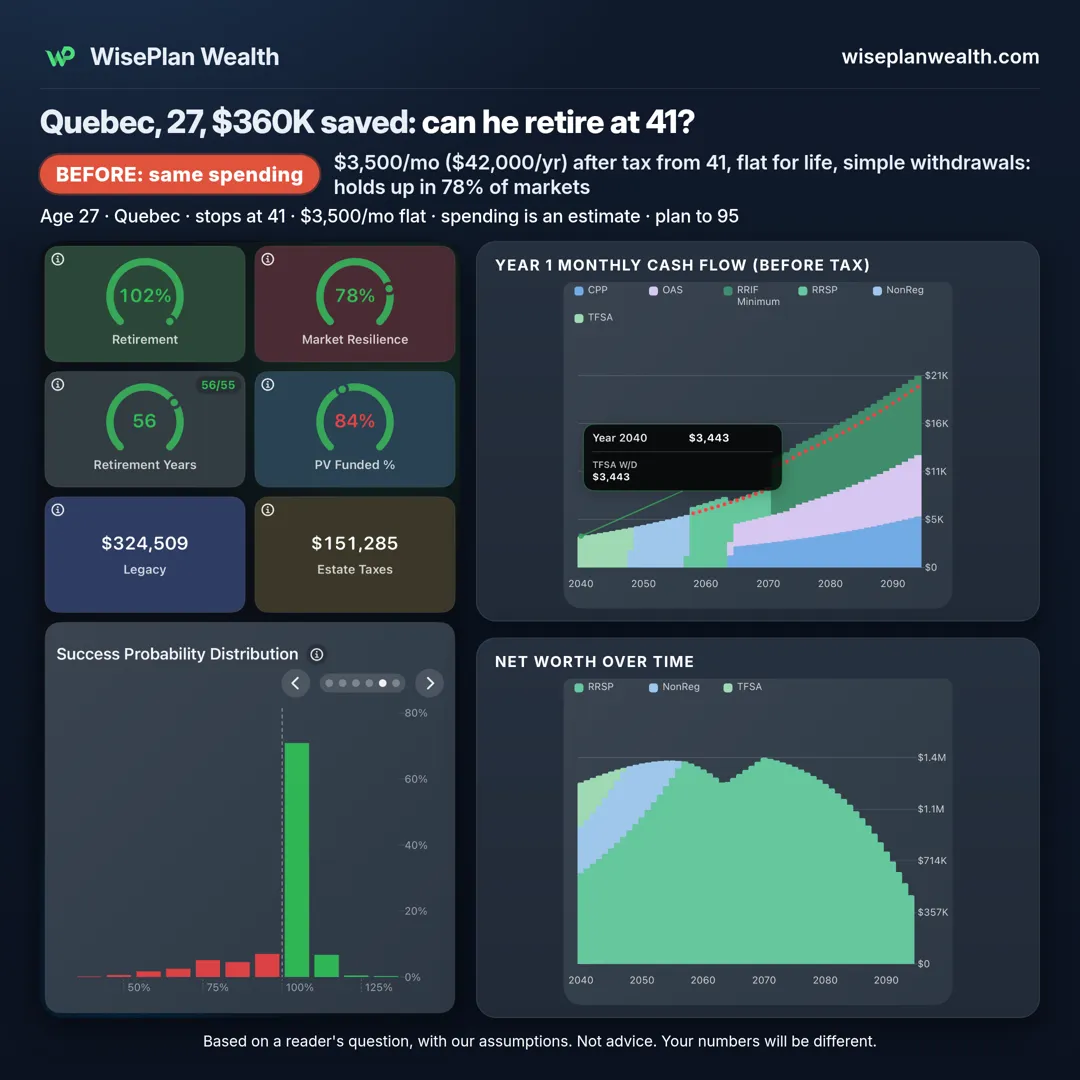
Before: same spending every year, simple withdrawals
$3,500/mo ($42,000/yr) after tax, flat for life, holds up in 78% of historical markets, with about $325,000 left at 95 in an average market.
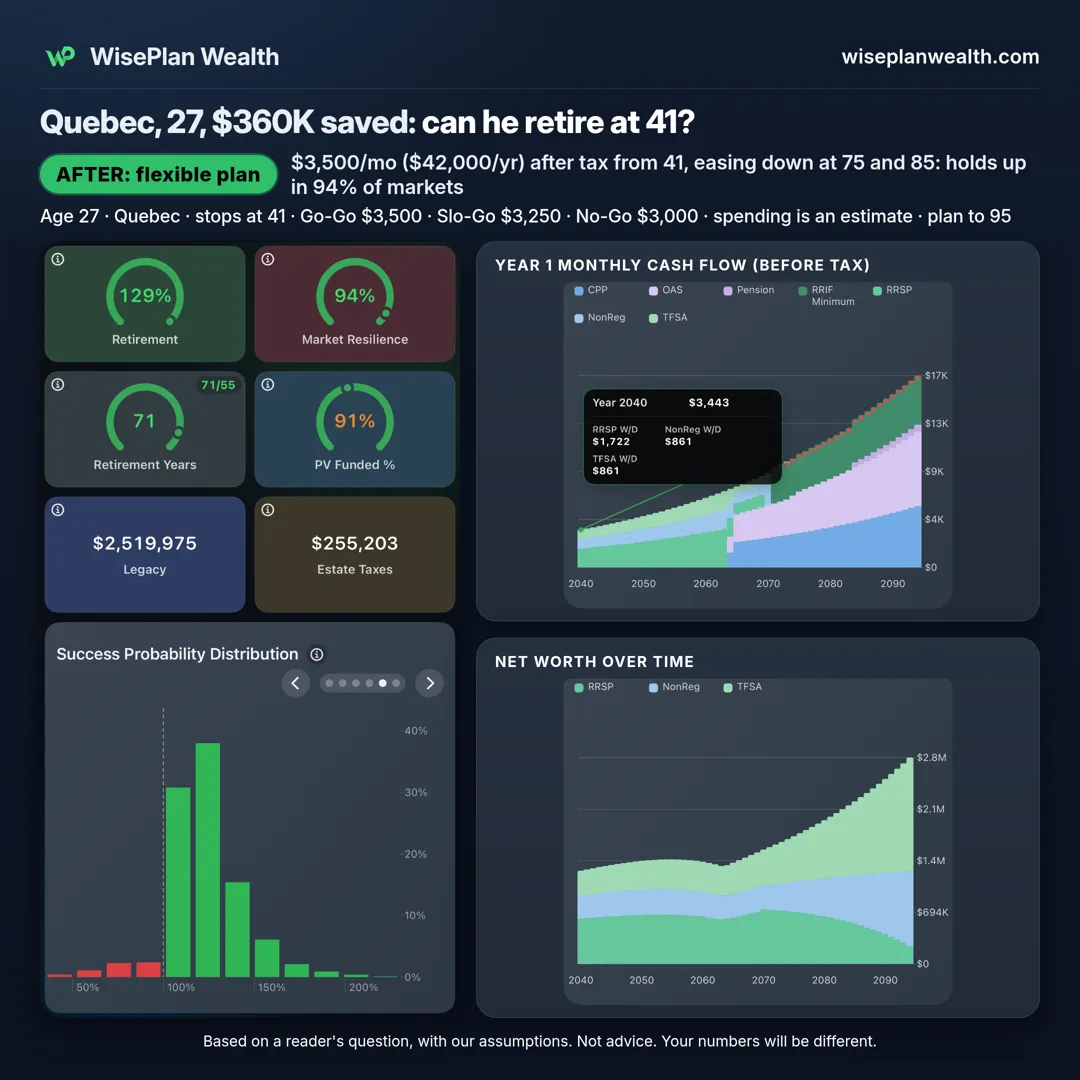
After: flexible plan, tax-smart withdrawals
- $3,500/mo from 41 until 75 (Go-Go years)
- $3,250/mo from 75 to 84 (Slo-Go years)
- $3,000/mo from 85 on (No-Go years)
That holds up in 94% of historical markets, with about $2.52 million left at 95 in an average market.
How we got there: the most the plan allows is $4,000/mo. We brought it down until it cleared 90% at $3,500.
First year after he stops (2040): the plan pays $3,443/mo, about $57 under his $3,500/mo target, with $0 tax. The flexible plan draws $1,722 from the RRSP, $861 from the non-registered account and $861 from the TFSA. The simple plan takes the same $3,443 from the TFSA alone.
Takeaway: Retiring at 41 works at about $3,500 a month, below our estimate of what he spends now. Counting his workplace pension, or working a few more years, would close the gap.
The before and after charts
Try the free calculators
- How much can I spend in retirement?
- Early retirement in Canada
- QPP vs CPP
- RRSP vs TFSA
- Quebec tax brackets
Run your own numbers
For the full picture, with how much you can safely spend and which account to draw from first, download WisePlan Wealth.
Names are invented and the details beyond the original question are our assumptions. The numbers come from a real run of the WisePlan Wealth app with its default return and inflation assumptions. This is an example, not advice, and your numbers will be different.