Retiring at 61 with $835,000 and an indexed pension in Saskatchewan
Short answer: About $835,000 plus an indexed nurse pension support about $7,050 a month ($84,600 a year) after tax from 61, when the money comes out in a tax-smart order.
A sample couple in Saskatoon, Saskatchewan, run in the WisePlan Wealth app. All amounts are after tax, in today's dollars.
Ross and Ruth have about $835,000 saved, and Ruth has a nurse's pension. They both want to stop working in mid-2029, when Ross is 61 and Ruth is 59. Instead of picking a budget and hoping it works, we looked for the most they can actually afford to spend.
The setup
- Ross (58) and Ruth (56), Saskatoon, Saskatchewan. Both stop working in mid-2029 (61 and 59)
- RRSP: $410,000 and $170,000
- TFSA: $95,000 and $90,000
- Non-registered: $70,000
- Saving: about $2,000/month until they stop
- Ruth's nurse pension: $1,600/month from 59, rises with inflation
- CPP (about $1,150 and $800/month) and OAS start at 65
- Plan runs to 95; spending is after tax, in today's dollars; default return and inflation assumptions
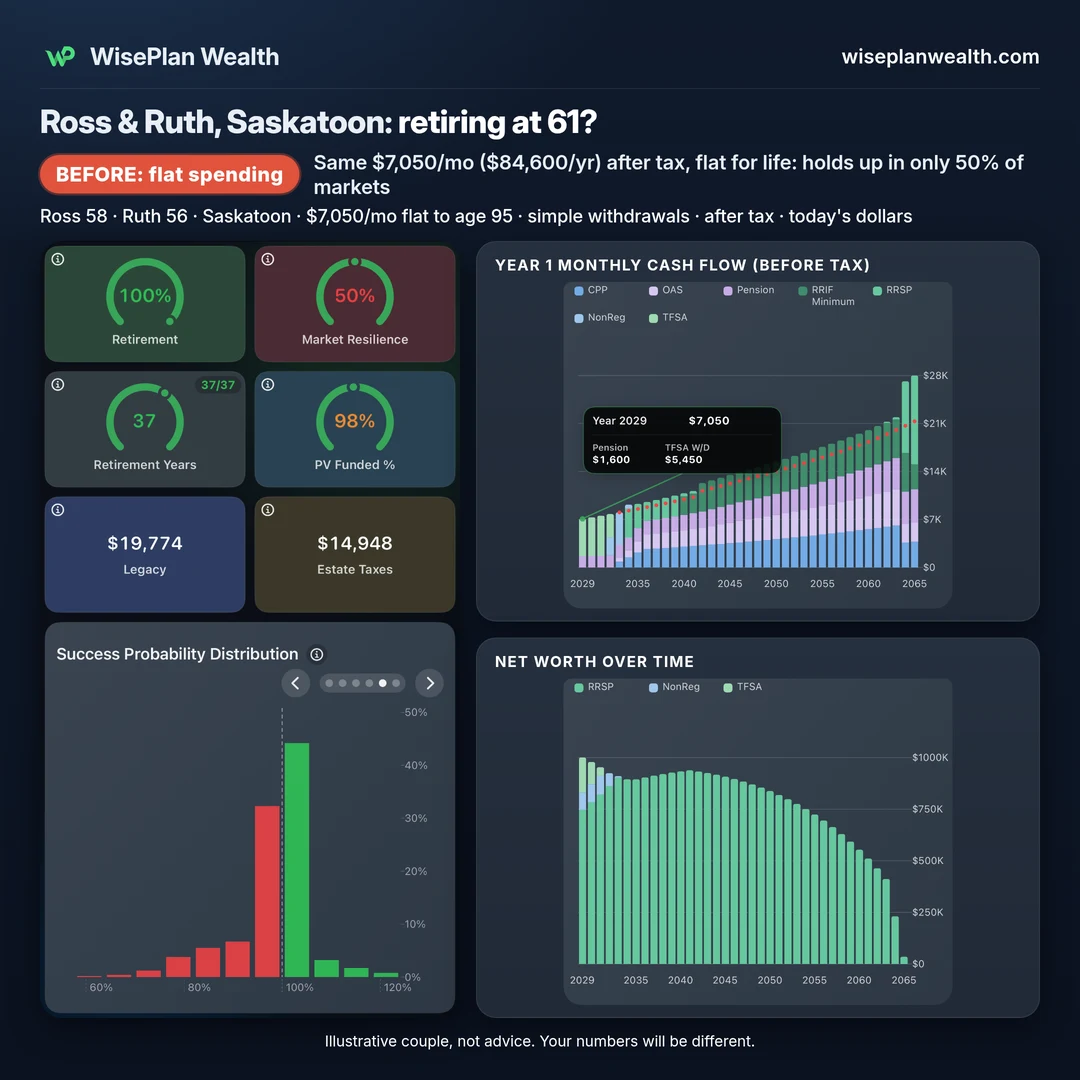
Before: same spending every year, simple withdrawals
$7,050/mo ($84,600/yr) after tax, flat for life → holds up in only 50% of historical markets, with about $20,000 left at 95 in an average market.
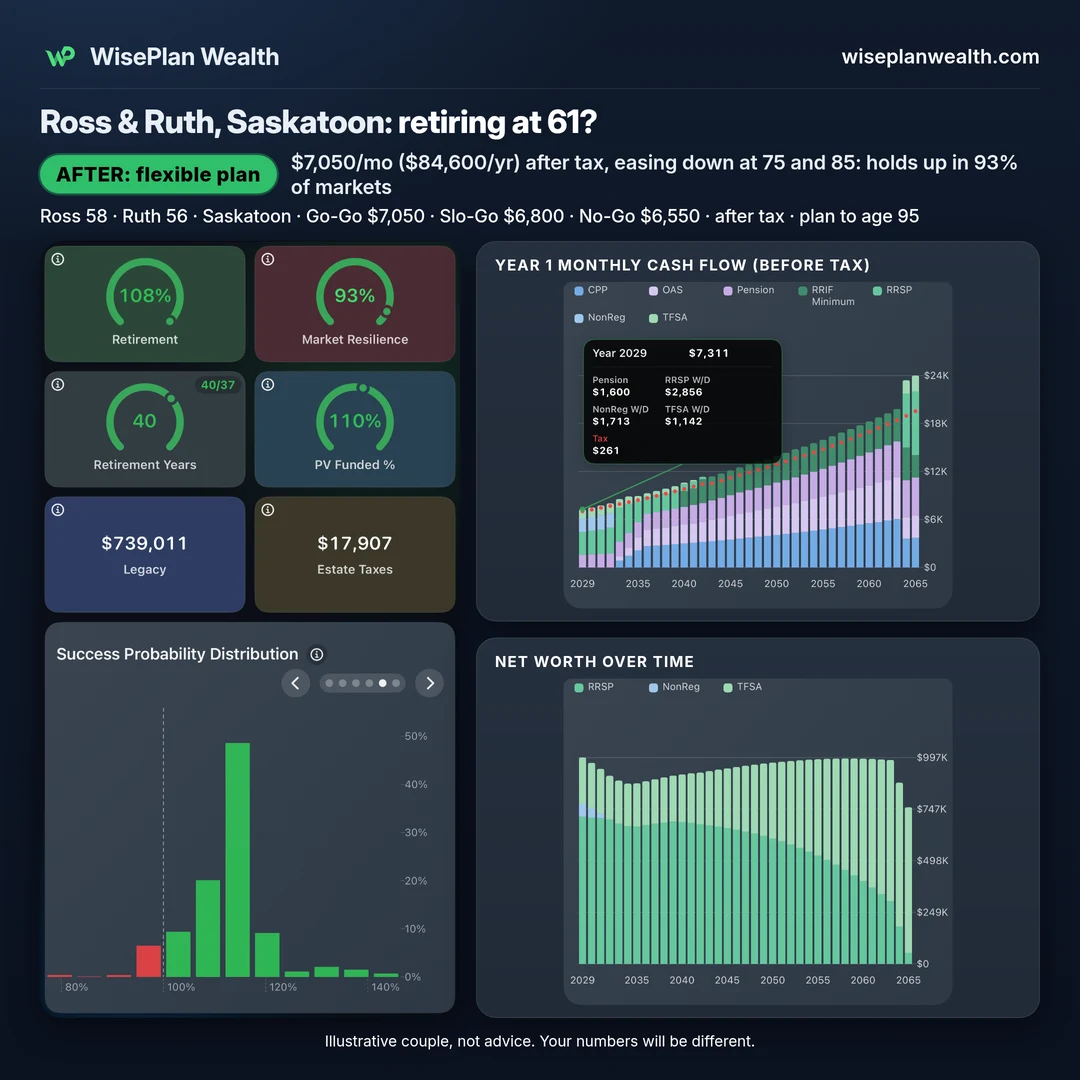
After: flexible plan, tax-smart withdrawals
- $7,050/mo from when they stop until 75 (Go-Go years)
- $6,800/mo from 75 to 84 (Slo-Go years)
- $6,550/mo from 85 on (No-Go years)
Holds up in 93% of historical markets, with about $739,000 left at 95 in an average market.
How we got there: the most the plan allows is $7,450/mo, but that holds up in only 51% of markets. We brought it down until it cleared 90% at $7,050.
First year after they stop (2029): about $7,311/mo before tax: Ruth's $1,600 pension, $2,856 from the RRSPs, $1,713 from the non-registered account and $1,142 from the TFSAs. Only about $261 goes to tax, which leaves $7,050.
Why the flexible plan holds up better: The simple way pays for everything beyond the pension from the TFSAs first ($5,450 a month in 2029), so the RRSPs sit and grow and come out later on top of CPP, OAS and the pension, at a higher tax rate. They have four to six lower-income years before CPP and OAS start. The flexible plan uses those years to draw from the RRSPs and the non-registered account at a low tax rate, keeps more in the TFSAs growing tax-free, and eases spending down a bit at 75 and 85.
Takeaway: About $835,000 plus an indexed nurse pension support about $7,050 a month ($84,600 a year) after tax from 61, when the money comes out in a tax-smart order.
The before and after charts
Try the free calculators
- Workplace (defined benefit) pension
- How much can I spend in retirement?
- When to take CPP
- When to take OAS
- CPP and OAS together
- Which account to draw from first
- RRIF minimum withdrawals
- Using your TFSA in retirement
- Tax in retirement (Canada)
More retirement stories
- Retiring at 57 on $1.45 million in Ontario: can they spend $10,000 a month?
- Retiring at 57 with a mine pension and $595,000 in Ontario
- Retiring at 60 with a workplace pension in BC: how much can they spend?
- Retiring at 55 on $945,000 in Ontario
- All Canada stories
Run your own numbers
The free calculators above each answer one piece. For the full picture, with how much you can safely spend, which account to draw from first and when to start CPP and OAS, download WisePlan Wealth.
This couple is an example, not real people. The numbers come from a real run of the WisePlan Wealth app with its default return and inflation assumptions. This is an example, not advice, and your numbers will be different.