Retiring at 62 with $785,000 and a teacher pension in BC
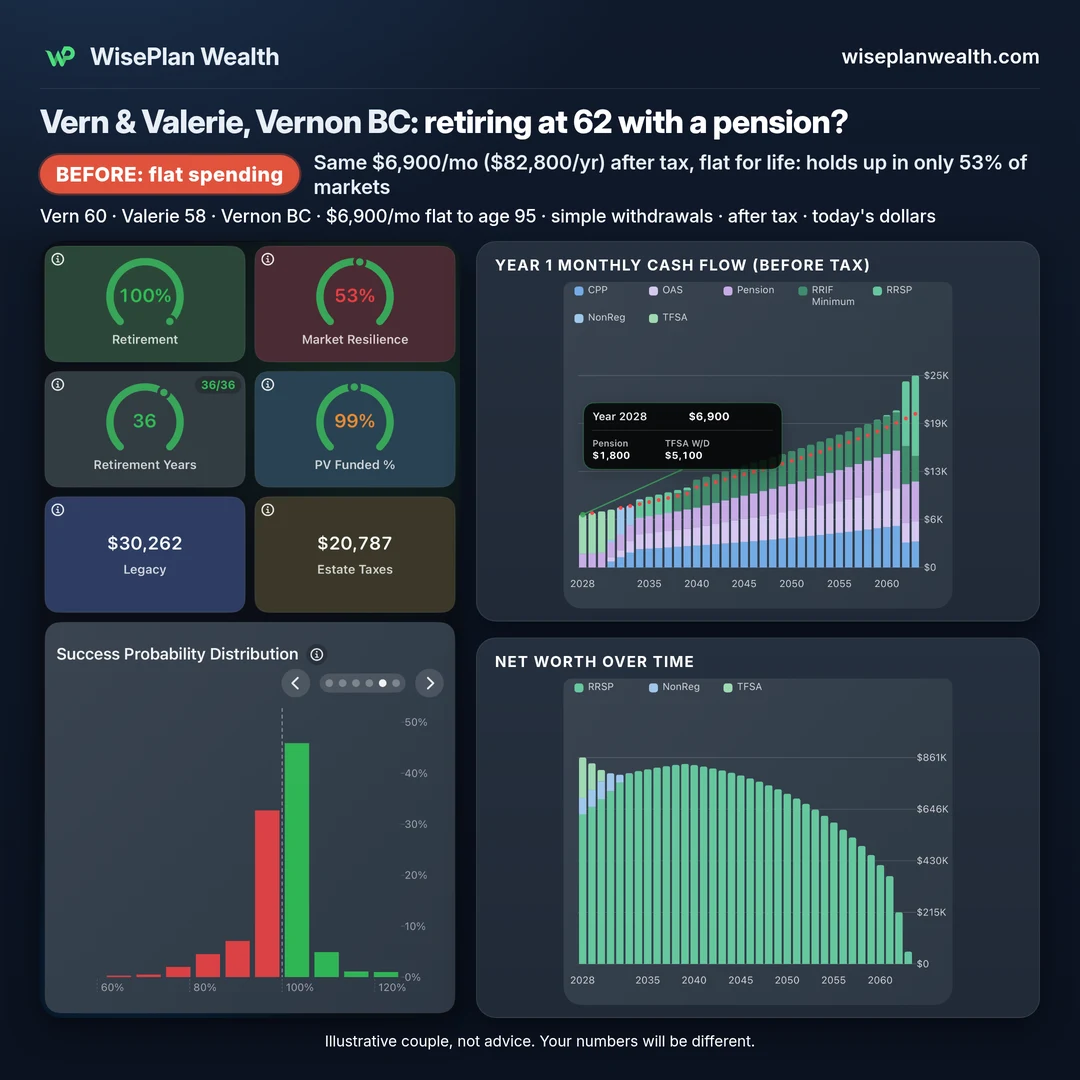
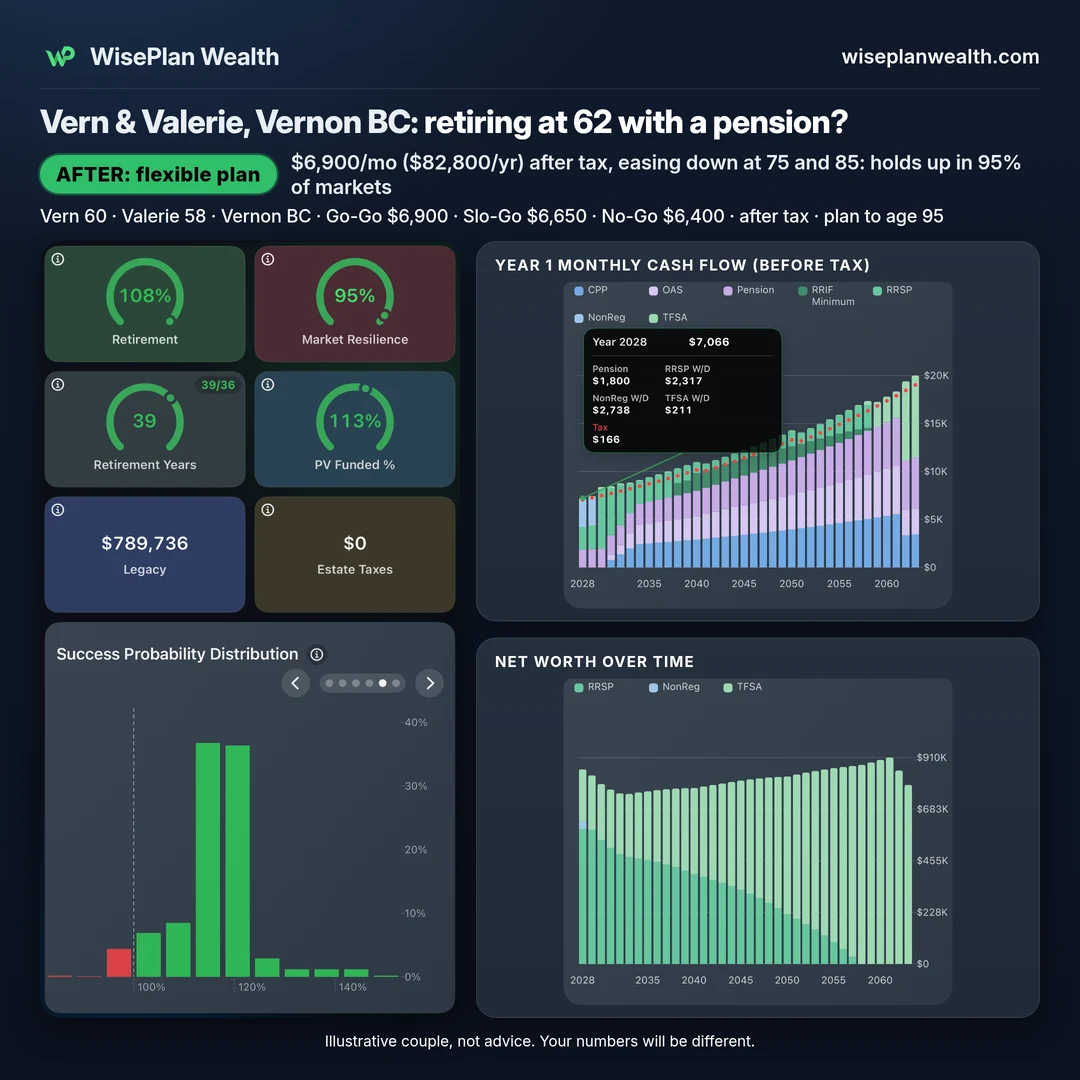
Short answer: About $785,000 and an indexed teacher pension can support about $6,900 a month ($82,800 a year) after tax from 62. The simple way pays for almost everything from the TFSAs first (about $5,100 a month in 2028, on top of the pension), so the RRSPs sit and grow and come out later on top of CPP, OAS and the pension, at a higher tax rate. Drawing from the RRSPs and the non-registered account in the low-income years before CPP and OAS start, keeping the TFSAs growing tax-free, and easing off a bit at 75 and 85, takes the same $6,900 from 53% to 95%, with far more left at 95.
A sample couple in Vernon, BC, run in the WisePlan Wealth app. All amounts are after tax, in today's dollars.
The situation
Vern is 60 and Valerie is 58. They live in Vernon, British Columbia. Both plan to stop working in mid-2028, when Vern is 62 and Valerie is 60. Valerie is a teacher, and her pension pays $1,800 a month from 60 and rises with inflation.
Here's what they have: RRSPs of $380,000 and $150,000, TFSAs of $100,000 and $95,000, and $60,000 in a non-registered account, about $785,000 in all. They're saving about $1,500 a month until they stop. CPP (about $1,100 and $750 a month) and OAS start at 65.
The worry
Valerie's pension covers part of the bills, but CPP and OAS are still three to five years away once they stop. Instead of checking whether a budget they had in mind works, they want to know how much they can actually afford to spend.
What the numbers say
All spending below is after tax, in today's dollars, with the plan running to 95. The plan gets tested against many historical market runs, the good starts and the bad ones.
Step 1: Spend the same amount every year, no matter what. $6,900 a month, flat, for life, taking money out the simple way. It holds up in only 53% of historical markets, with about $30,000 left at 95 in an average market.
Step 2: Same starting amount, but a more flexible plan, with withdrawals timed to keep tax low:
- $6,900 a month in the earlier years
- $6,650 a month from 75 to 84 (the Slo-Go years)
- $6,400 a month from 85 on
To find that $6,900, we pushed spending as high as the plan allows ($7,300, which holds up in only 50% of markets), then brought it down until the plan held up in more than 90%.
That plan holds up in 95% of historical markets, with about $790,000 left at 95 in an average market. In 2028, their first year retired, they'd draw about $7,066 a month before tax: Valerie's $1,800 pension, $2,317 from the RRSPs, $2,738 from the non-registered account and $211 from the TFSAs. Only about $166 goes to tax, which leaves the $6,900.
The takeaway
About $785,000 and an indexed teacher pension can support about $6,900 a month ($82,800 a year) after tax from 62. The simple way pays for almost everything from the TFSAs first (about $5,100 a month in 2028, on top of the pension), so the RRSPs sit and grow and come out later on top of CPP, OAS and the pension, at a higher tax rate. Drawing from the RRSPs and the non-registered account in the low-income years before CPP and OAS start, keeping the TFSAs growing tax-free, and easing off a bit at 75 and 85, takes the same $6,900 from 53% to 95%, with far more left at 95.
Try the free calculators
- Workplace (defined benefit) pension
- How much can I spend in retirement?
- When to take CPP
- When to take OAS
- CPP and OAS together
- Which account to draw from first
- RRIF minimum withdrawals
- Using your TFSA in retirement
- Tax in retirement (Canada)
More retirement stories
- Retiring at 58 on $1.09 million with no pension in Ontario
- Retiring at 62 with $790,000 and a pension in Nova Scotia
- Retiring at 59 on $945,000 with no pension in Ontario
- Retiring at 62 with $810,000 and an indexed pension in Manitoba
- All Canada stories
Run your own numbers
The free calculators above each answer one piece. For the full picture, with how much you can safely spend, which account to draw from first and when to start CPP and OAS, download WisePlan Wealth.
This couple is an example, not real people. The numbers come from a real run of the WisePlan Wealth app with its default return and inflation assumptions. This is an example, not advice, and your numbers will be different.