Retiring at 50 on $2.1 million as a renter in New York City
Short answer: With about $2.1 million saved at 42, a single New York City renter who stops work at 50 can spend about $8,350 a month ($100,200 a year) after tax, more than the $75,000 to $85,000 he spends now.
Based on a real question on Reddit, filled in with our assumptions and run in the WisePlan Wealth app. All amounts are after tax, in today's dollars.
A reader in r/FinancialPlanning, 42, single and renting in New York City, asked when he could stop working. He has about $2.1 million saved and spends $75,000 to $85,000 a year. We'll call him Theo. We looked for the most he could spend if he stopped at 50.
The setup
- From the question: age 42, single, renting in Brooklyn (about $3,000/month rent), $140,000 salary
- From the question: $140,000 cash, $1.2 million taxable, $742,000 pre-tax (401(k)/IRA), $24,000 HSA
- Our assumptions: he stops working in mid-2034 at 50 and keeps saving $24,500/yr to his 401(k) and $20,000/yr to taxable until then
- Our assumptions: cash folded into the taxable account (about $980,000 cost basis), and the HSA treated as a Roth-type account
- Our assumptions: rent is part of his spending, he rents for life, and Social Security is about $2,700/month at 67 (an estimate, not his record)
- Plan runs to 95, with default return and inflation assumptions
See the answer, year by year
Loading the interactive plan…
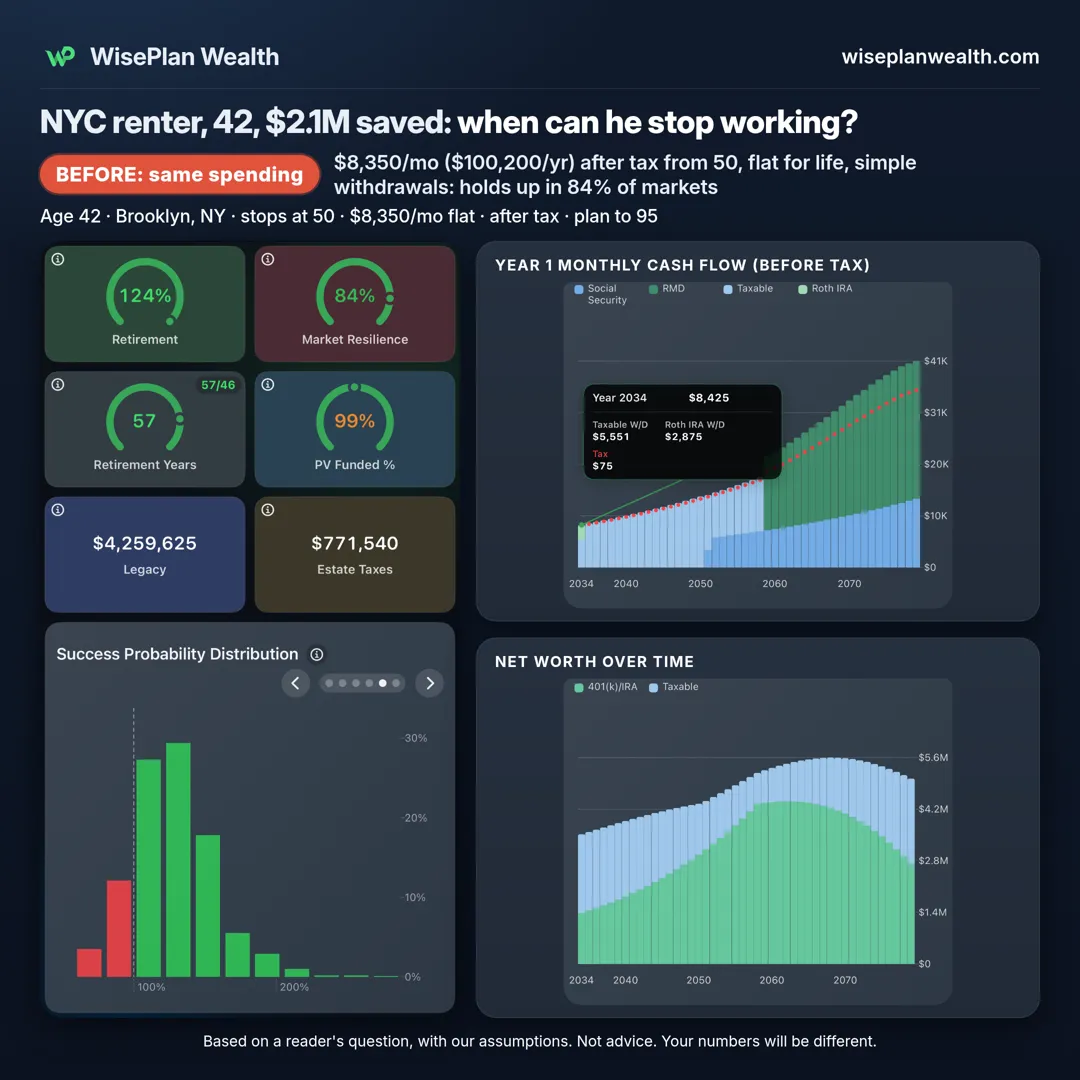
Before: same spending every year, simple withdrawals
$8,350/mo ($100,200/yr) after tax, flat for life, holds up in 84% of historical markets, with about $4.26 million left at 95 in an average market.
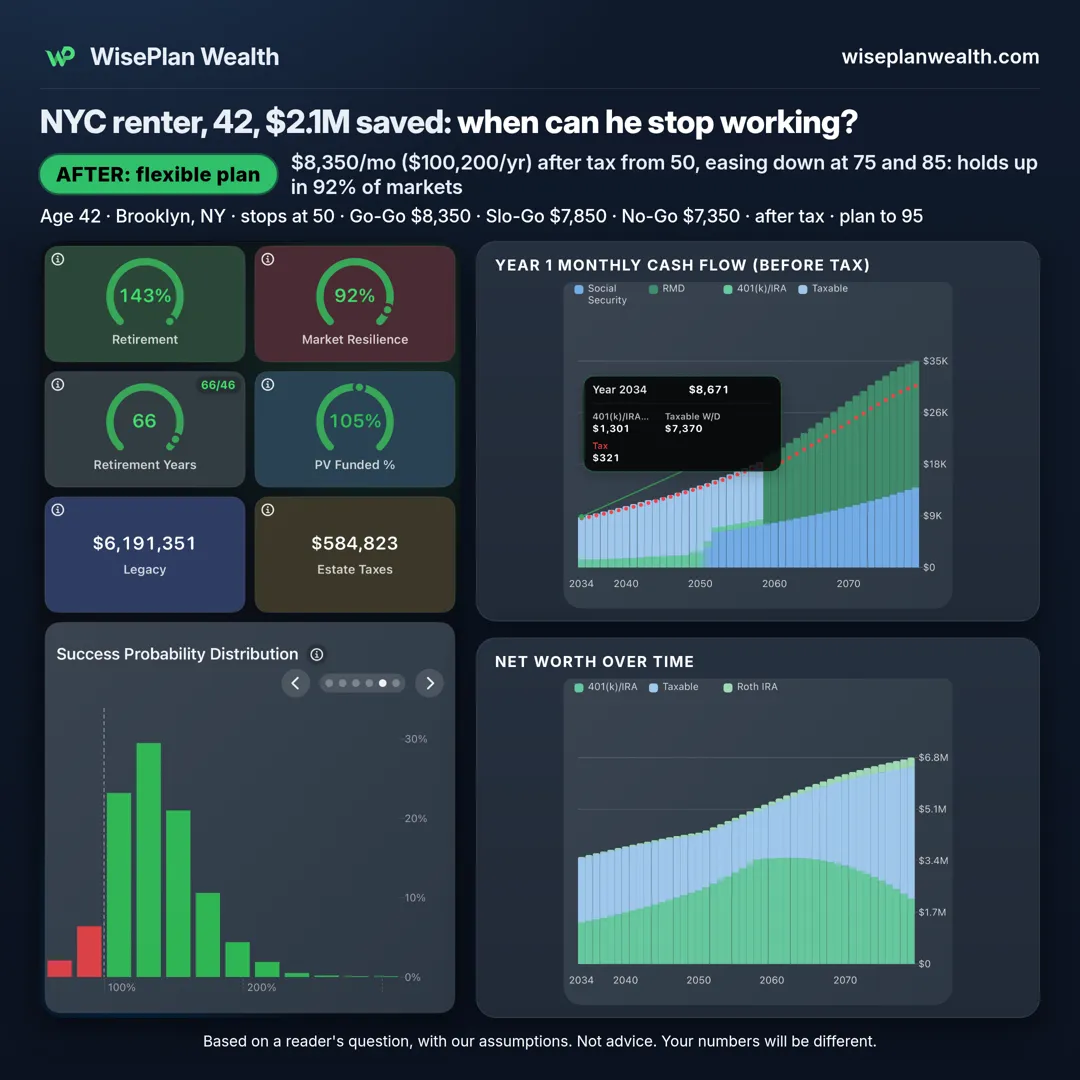
After: flexible plan, tax-smart withdrawals
- $8,350/mo from 50 until 75 (Go-Go years)
- $7,850/mo from 75 to 84 (Slo-Go years)
- $7,350/mo from 85 on (No-Go years)
That holds up in 92% of historical markets, with about $6.19 million left at 95 in an average market.
How we got there: the most the plan allows is $10,150/mo. We brought it down until it cleared 90% at $8,350.
First year after he stops (2034): about $8,671/mo before tax: $7,370 from the taxable account and $1,301 from the 401(k)/IRA. About $321 goes to tax, which leaves $8,350.
Takeaway: At his current $75,000 to $85,000 a year, 50 looks comfortable, with room to spare for higher NYC costs or a lower-paid second career.
The before and after charts
Try the free calculators
Run your own numbers
For the full picture, with how much you can safely spend and which account to draw from first, download WisePlan Wealth.
Names are invented and the details beyond the original question are our assumptions. The numbers come from a real run of the WisePlan Wealth app with its default return and inflation assumptions. This is an example, not advice, and your numbers will be different.